Beyond the Rating Drop: Securing Physical Margins in the August Pivot
Condition ratings are slipping just as pod-fill begins. Here is how U.S. grain farmers can manage basis and logistics risk before the harvest rush.
Agrodity quick take
Market sentiment is shifting as the latest USDA reports reflect the first real signs of late-summer heat stress, with corn and soybean conditions dropping 4% and 3% respectively this week. While futures have reacted with profit-taking, the real story for farmers is in the physical market where export demand is firming just as river logistics start to tighten ahead of harvest.
What's happening
- Condition Decline: U.S. corn and soybean condition ratings both fell to 63% Good-to-Excellent, signaling that the late-July heat dome trimmed the top-end yield potential across the I-80 corridor.
- Critical Window: Soybeans are entering the high-stakes pod-fill stage with 47% of the crop setting pods, making August precipitation the primary driver of price discovery for the next 30 days.
- Export Floor: Fresh demand has emerged as China and 'unknown destinations' booked over 250,000 tons of U.S. soybeans this week, providing a floor for the physical market despite technical selling on the board.
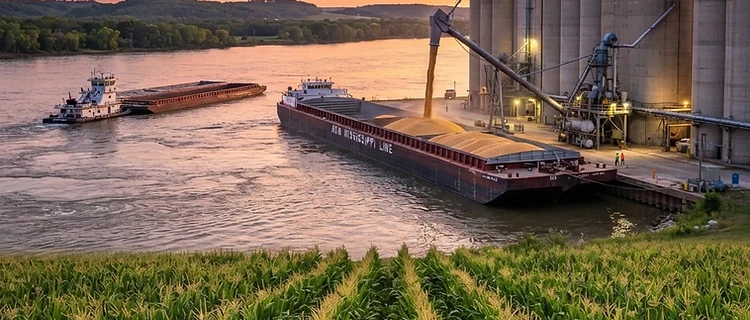
- Logistics Headwinds: Mississippi River levels at St. Louis and Cairo are trending toward seasonal lows; draft restrictions are already being discussed by barge lines, which could spike freight costs in September.
- Wheat Saturation: In the Northern Plains, record-level spring wheat yields are threatening to saturate local storage, potentially leading to a significant basis weakening at regional elevators.
Why it matters for grain marketing
For the U.S. producer, a 'very good' crop is largely already priced into the December and November contracts. The recent drop in condition ratings has not triggered a massive rally because the market still anticipates one of the largest crops in history. However, for physical sellers, the logistics risk is becoming the dominant variable. If river levels remain low, the cost to move grain to the Gulf will increase, widening the basis and eroding your cash price even if futures remain stable.
The export interest from China is a positive signal, but it relies on efficient movement through the inland waterway system. Farmers who ignore the basis today may find themselves 'long the crop but short the space' by October. The gap between the board and the bin is where the 2026 harvest will be won or lost.
Agrodity playbook
- Lock in Basis: Target 'Basis-Only' contracts for at least 20% of your expected soybean production to hedge against a logistics-driven basis blowout if river levels continue to decline.
- Prioritize Wheat Movement: For growers in the Dakotas and Minnesota, move record-yield spring wheat into commercial channels or prepay storage early to avoid the 'harvest wall' at the elevator.
- Monitor the 10-Day Window: If the promised cooler weather fails to bring significant moisture to the Western Corn Belt by mid-August, look for a technical bounce in soybean futures to price another 10% of the crop.
- Compare Bids: Use the Agrodity marketplace to compare local elevator bids against domestic processor bids; crushers are currently paying a premium in several regions to secure supply before export competition intensifies.